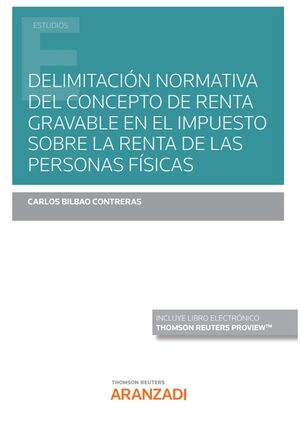
Vista previa: DELIMITACIÓN NORMATIVA DEL CONCEPTO DE RENTA GRAVABLE EN EL IMPUESTO SOBRE LA RE
This website uses cookies, both its own and those of third parties, to improve your browsing experience. If you continue, we will consider you accept its use.More information